PAN card applicationsPan-IndiaA national citizen service, brought to mobile
Strategy, Design & Web
Discovery, advisory, UX design and websites
Software & Platform Engineering
Custom software, SaaS, enterprise systems and modernisation
Mobile Application Development
iOS, Android and cross-platform apps
Digital Commerce
Online stores, Shopify, shopping apps and quick commerce
AI, Data & Intelligent Automation
Agents, GenAI, automation and data platforms
Cloud & Platform Operations
Managed cloud, DevOps, SRE and FinOps
Cybersecurity & Risk Management
VAPT, zero-trust and governance, risk & compliance
Digital Marketing & Growth
Search, AI visibility, paid media and lifecycle
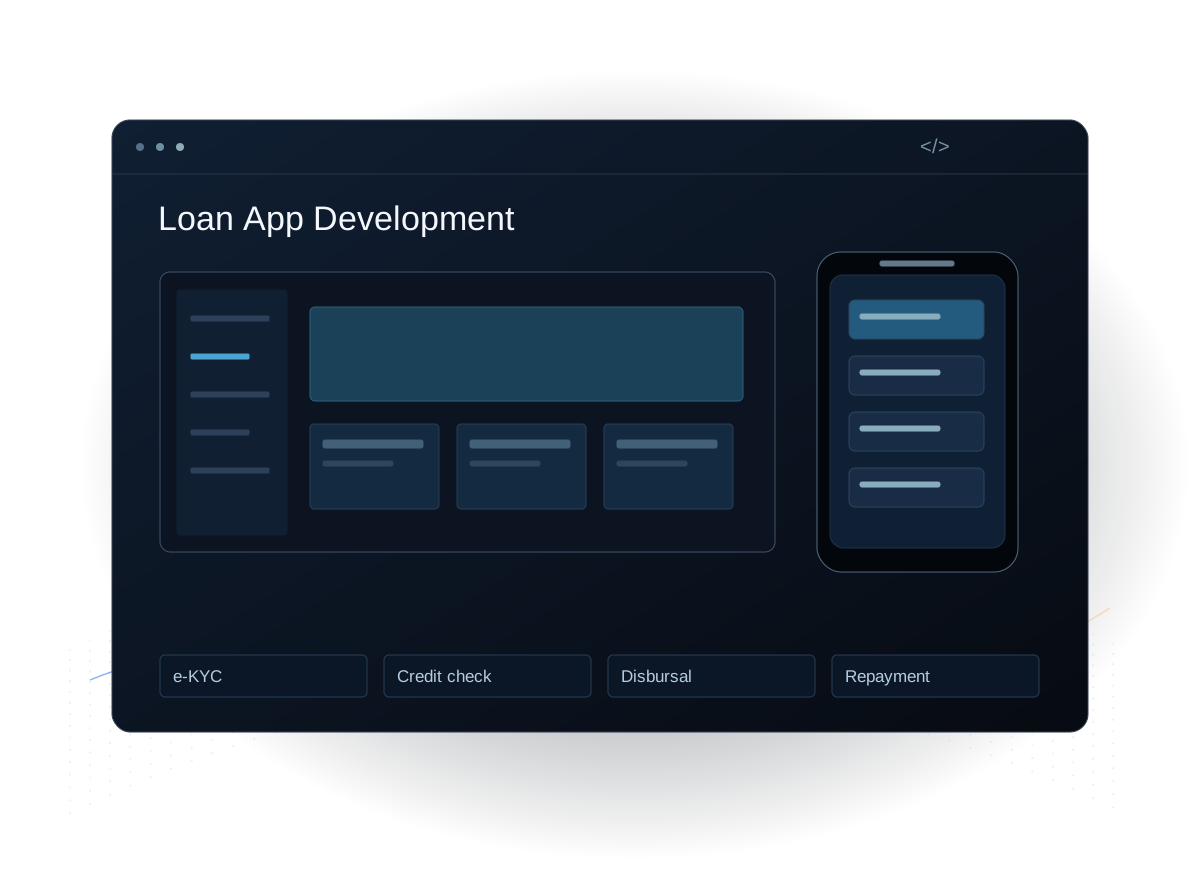
Mindrops builds instant personal loan and smartphone EMI financing apps, with the borrower app, partner app, credit decisioning, collections and admin panel behind them, designed around RBI’s digital lending rules.
Clients

Mindrops designs and builds digital lending platforms: borrower apps for Android and iOS, PAN and Aadhaar e-KYC, credit bureau checks, rules-based approvals, the Key Fact Statement and e-sign, disbursal, e-NACH or UPI AutoPay repayments, reminders and a loan admin panel. Each build follows the lender’s product rules and RBI’s digital lending directions.
Projects from closely related areas of our work.

AI · Accounting
A Mindrops document-intelligence product that extracts transactions, line items, totals and dates to Excel, CSV, JSON or XML through a REST API, with human-in-the-loop review.
Delivers 99% extraction accuracy on supported documents across bank statements, invoices and receipts.
AI · Financial Validation
A read-only validation platform that runs 30+ checks across seven detection modules — including eight statistical anomaly methods — with one governed review workspace.
Every client close is now checked the same way and tracked from one dashboard, with 100% of findings carrying an audit trail for sign-off.
Mobile OTP sign-up, PAN verification, Aadhaar e-KYC or video KYC, selfie and liveness checks, with consent captured and logged at every step.
Credit bureau pulls (CRIF, CIBIL), bank-statement inputs and a configurable rules engine that approves, rejects or refers each application.
Key Fact Statement with the all-in APR, loan agreement generation and Aadhaar e-sign, stored against the loan record.
Disbursal to the borrower’s verified bank account, e-NACH and UPI AutoPay mandates, payment links, part-payment and foreclosure.
EMI reminders over SMS, WhatsApp, email and push, bounce handling, overdue buckets and collection workflows for agents.
An admin panel for applications, credit review, loan accounts, schedules, charges, customer support and the reports lenders and auditors ask for.
For device financing: a retailer app for in-store onboarding and approvals, EMI plans, device lock on default and optional protection plans.
Lenders moving from branch or DSA sourcing to an app, who need onboarding, underwriting and loan servicing that their credit and compliance teams can sign off.
Teams partnering with a regulated lender, who need a borrower app, lender integrations and clean separation of who holds the loan, the money and the data.
Businesses selling smartphones or appliances on EMI, who need a retailer app for in-store onboarding, instant approvals and repayment tracking.
Institutions adding instant personal loans or credit lines to an existing customer base, connected to their core systems and risk rules.
Fintech lending platform
A customer app, vendor app and admin panel from one team, with KYC, CIBIL credit checks and automated loan approvals.
From the client’s review
“Fintech projects have a lot of layers and it was good to work with a team that understood the credit and lending side of things.”
We write down the loan products, borrower journey, lender and partner roles, money flows and every integration, and agree what goes into the first release.
Borrower, partner and admin flows are prototyped, and eligibility rules, KFS content, consent screens and permissions are reviewed with your credit and compliance teams.
App, backend and admin ship in increments against KYC, bureau, e-sign and mandate sandboxes, with end-to-end loan tests from application to closure.
Production keys, Play Store personal-loan declaration and a pilot cohort come first, then wider rollout with monitoring, support and product changes.
Message, call or email us about your project. We'll go through your objectives, suggest the most cost-effective approach and give you a rough timeline and cost.
Reach out today. We'll get back to you as quickly as possible.
Tell us about your loan products, your lending licence or partner, and the integrations you already have. We reply as quickly as possible with a recommended first release.
An engineer will respond as quickly as possible.
Have a defined scope? Get a quote